(NON) CONFERENCE SEASON: RESTORE BRITAIN SHARPENS THE TAX AXE
Read more
October 13, 2026 | 9 min read
Author: Andy Wood
If the robots are taking the jobs, should they pick up the tax bill?
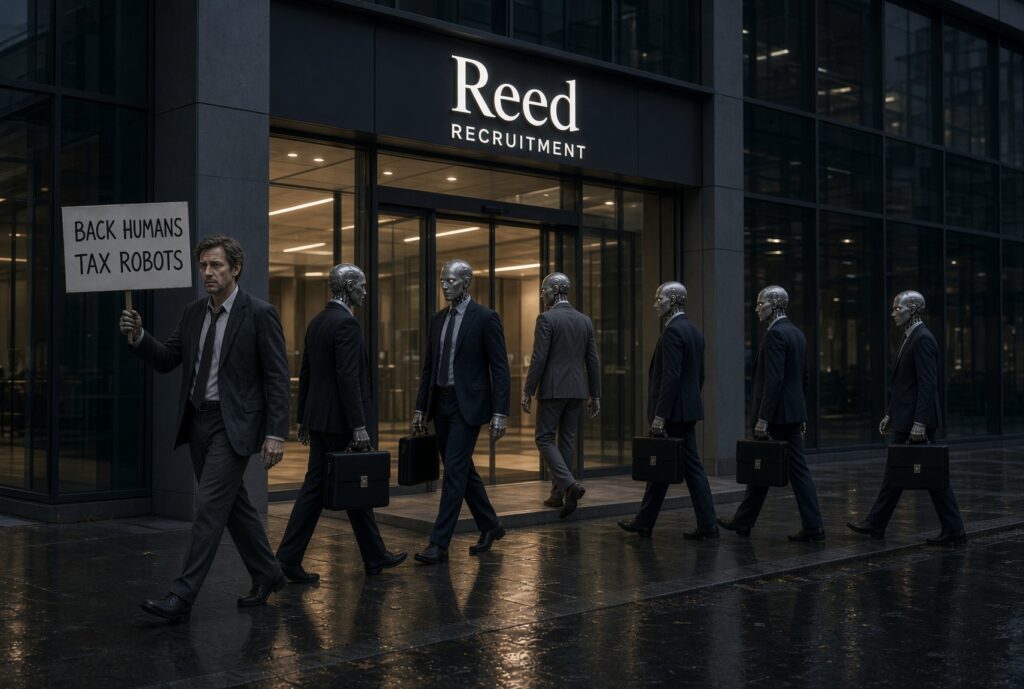
James Reed, chairman and chief executive of Reed, thinks there is a case. In The Times on 13 October, he calls for taxes on AI and automated services to help reduce the cost of employing young people.
His slogan is “back humans, tax robots”. His more specific suggestion is to examine transaction-based levies on automated services and AI tokens, drawing an analogy with VAT, and use the revenue to support hiring.
Reed’s concern is a “missing generation”: young people denied the first jobs through which they acquire experience and become tomorrow’s business leaders.
I have been circling this subject on Breaking Tax for the past year. Reed brings a welcome focus on the people trying to enter work now. But his proposal also brings together two problems I keep returning to: how to sustain employment, and how to finance a state whose revenues depend heavily on it.
I share the concern. I am less persuaded that a levy on AI transactions gives us the answer.
The Times reports Reed figures showing graduate vacancies falling from 180,000 to 50,000 over four years, a drop of 72%.
Those are Reed’s reported figures, and, even if right, they are not proof that AI caused the whole decline. Hiring costs and wider business conditions matter too. But the concern deserves attention without waiting for a perfect explanation of every missing vacancy.
Consider a professional firm. A junior employee’s first attempts at research, drafting or analysis are often slower than a senior colleague would like. They require supervision. Someone has to correct the mistakes.
That is part of how the firm produces its next generation of experienced professionals.
If AI can complete the immediate task more cheaply, removing the junior role may make sense for this year’s budget. Across an entire profession, however, that decision could leave a shortage of people who have learnt how to exercise judgement.
A firm can try to recruit experienced staff from elsewhere. An economy cannot have every employer doing that indefinitely.
This is where Reed’s argument has force. The cost of losing an entry-level role may extend beyond the salary that disappears today. It includes the expertise that might never develop.
Employers will need to redesign training around AI. Keeping obsolete tasks alive is hardly an ambition. Giving young people responsibility, supervision and opportunities to learn should be.
Reed’s proposal is more specific than sending a self-assessment tax return filing notice to a warehouse robot. He is looking at business expenditure on AI products and automated services.
That gives policymakers an identifiable transaction to examine. It also creates some awkward questions.
Ordinary VAT is generally recoverable by a VAT-registered business to the extent that purchases support taxable supplies, subject to the usual conditions. HMRC’s guidance explains the principle.
So, if an AI levy genuinely followed VAT, including input-tax recovery, it would often fail to create the lasting additional cost for a business purchaser that the proposal appears to envisage. If recovery were blocked, or the levy sat outside VAT, it would work differently. The distinction matters.
There is also a difference between taxing expenditure and taxing gains.
Imagine two firms buying the same AI service. One uses it to remove junior roles. The other uses it to help newly recruited graduates produce better work. A transaction levy could charge both identically.
Now imagine a large business developing its own system while a smaller competitor buys access from an external provider. A tax on purchased services would need rules for internal provision, or risk treating economically similar activity differently.
None of that makes legislation impossible. It means the government must identify what it wants to tax and why. A charge on AI usage, a charge on displaced employment and a charge on exceptional profits are different policies.
And calling the payer a robot does not settle who bears the cost. Depending on competition and pricing, a levy could fall on shareholders, business customers, consumers or workers.
In The (Tax) Rise of the Robots, I explored the implications of an economy producing more with fewer people on the payroll. A state accustomed to collecting income tax and National Insurance from employment would have to adapt.
That does not require a future in which nobody works.
In Will AI make ‘income tax redundant within five years’?, I questioned the dramatic timetable. Technological predictions do not become financial forecasts merely because someone attaches a date to them.
The more immediate concern is gradual erosion. Fewer first jobs, slower progression and weaker earnings than would otherwise have occurred. Reed’s intervention fits that argument rather well.
There is an optimistic possibility too. AI could help businesses expand, create new services and employ people in roles that do not yet exist. Higher productivity could support higher incomes and receipts.
The point is to prepare for different outcomes. Assuming that every task automated means a job lost is too crude.
Assuming the tax base will look after itself is equally unsatisfactory.
The reassuring response is that lower wage bills mean higher profits, so corporation tax collects the money instead.
I examined that assumption in Part Two of my UBI series, Who Pays for UBI?.
It depends on where the gains appear.
Competition may pass savings to customers through lower prices. Some returns may accrue to overseas technology suppliers. Others may increase asset values without generating an immediate UK tax receipt.
Cheaper services can improve living standards. They do not automatically replace lost payroll revenues pound for pound.
Nor should we assume the opposite. Lower prices can stimulate demand, and businesses may reinvest savings. The outcome depends on how the economy responds.
That is why I favour examining profits, capital income and economic rents, meaning returns above those needed to reward investment, alongside the incentives already built into the tax system.
The IMF has similarly argued against a blunt AI-specific tax, while supporting stronger capital taxation and reconsideration of tax incentives that encourage displacement. That still leaves difficult choices over investment, enforcement and international coordination. It gives us a more useful starting point than taxing every purchase with “AI” on the invoice.
Usually quite quickly.
If machines do more of the work, perhaps everyone should receive a Universal Basic Income. The proposition is attractive. It also contains several separate arguments that need testing.
I explored these in my three-part series, The Future’s Been Sold.
Part One distinguishes a genuinely universal payment from targeted guaranteed income, a negative income tax and a dividend from shared assets. These designs have different costs and purposes.
The evidence discussed there gives reasons to take unconditional cash seriously. Greater security can give people room to plan, retrain or make different choices about work. It does not establish that a permanent national UBI, financed through the tax system, will reproduce the results of a smaller trial.
Nor does an income payment solve Reed’s particular problem. A young person might receive financial support and still struggle to acquire professional experience. Income security and access to a career require separate attention.
Part Two also distinguishes a full UBI from an AI dividend. A dividend could distribute identifiable returns from particular assets or activities. A permanent income guarantee needs reliable funding even when those returns disappoint.
That is quite a difference to hide inside the promise that “AI will pay”.
In Part Three, Could UBI Work in the UK?, I considered the other side of the ledger. That is, the behaviour of those financing the payments.
A nationwide programme affects taxpayers as well as recipients. Changes in investment, working patterns and location can alter the revenues available. The result cannot be inferred simply by multiplying today’s tax base by tomorrow’s higher rates.
That does not establish that any particular tax rise will fail. It does require policymakers to examine behavioural effects rather than assuming them away.
There is a practical choice too. For a fixed budget, universal payments spread support widely. Targeted support can direct more towards people with greater needs, although eligibility rules bring their own complexity.
Reed’s immediate concern makes the distinction especially relevant. Helping young people enter work is a more focused objective than replacing the relationship between earnings and welfare across the whole population.
I would start by examining the cost of providing a first job and meaningful training. Any further hiring relief should be assessed against existing support and designed to encourage additional opportunities, with attention to employers simply substituting one eligible worker for another.
I would also ask employers how they intend to train people when AI performs more of the work through which juniors previously learnt. A cheaper hire with no route to competence is a limited achievement.
On revenue, I would test proposals against where the gains actually arise and who ultimately pays. An AI levy should earn its place through evidence about revenue and behaviour. Its futuristic name is no recommendation.
And I would keep support for displaced workers in the discussion. The people affected will include experienced employees as well as graduates. Some will need time and money to move into different work.
Reed has put a pressing problem in front of the government. The tax system should help people through technological change, and its dependence on employment deserves serious scrutiny.
My test of his proposal is straightforward. Would it help a young person secure a first job, without making the tools that could help them succeed needlessly expensive?
The graduate needs an opportunity. The Treasury needs a sustainable tax base. A tax on an AI transaction has to demonstrate how it helps deliver both.
For the fuller discussion, my UBI series is available on Breaking Tax:
Published 1 October 2026
Read More
Published 23 September 2026
Read More
Published 17 September 2026
Read More
Published 5 September 2026
Read More
Published 30 August 2026
Read More
Published 18 June 2026
Read More